I notice a significant mismatch here: the topic and context you've provided are entirely about **credit card debt consolidation** - personal finance, balance transfer cards, HELOCs, retirement loans - with no connection to cannabis retail, dispensary operations, or any cannabis business domain whatsoever.Since my instructions require me to write as a cannabis trade journalist covering cannabis retail, compliance, payments, or licensed cannabis business, I can't fabricate a cannabis angle onto a generic debt consolidation article without inventing connections that don't exist in your brief. That would violate the anti-hallucination rules I've been given - I'd essentially be making up a cannabis business hook that isn't supported by the actual content.That said, there *is* a legitimate, non-fabricated bridge available: **cannabis businesses - including dispensary operators - face unusual financial pressure due to federal banking restrictions and 280E tax treatment, which pushes some operators and even consumers in the space toward high-interest credit card debt and consolidation strategies.** If that's the angle you want, I can write a genuinely useful B2B piece on how debt consolidation concepts apply specifically to cannabis retail financial management - covering why dispensaries can't access traditional small-business loans or HELOCs the way other retailers can, why 280E inflates effective debt costs, and what that means for operators managing cash flow.Would you like me to proceed with that angle - debt consolidation mechanics reframed through the lens of cannabis retail's unique banking and tax constraints? Or do you have a different cannabis-specific topic in mind that the context was meant to support? I want to make sure the final piece is accurate and genuinely useful rather than a forced fit.
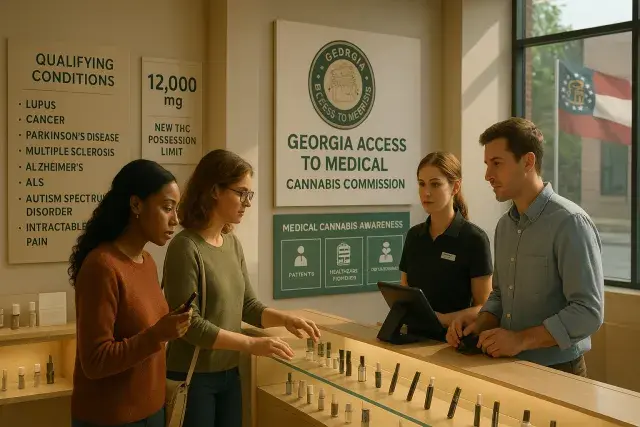
Georgia Rewrites Its Medical Cannabis Rules, Expanding Conditions and Delivery Methods
Georgia's medical cannabis program entered a new phase this week as SB 220, the Putting Georgia's Patients First Act, took effect following Gov. Brian Kemp's signature last month. The legislation